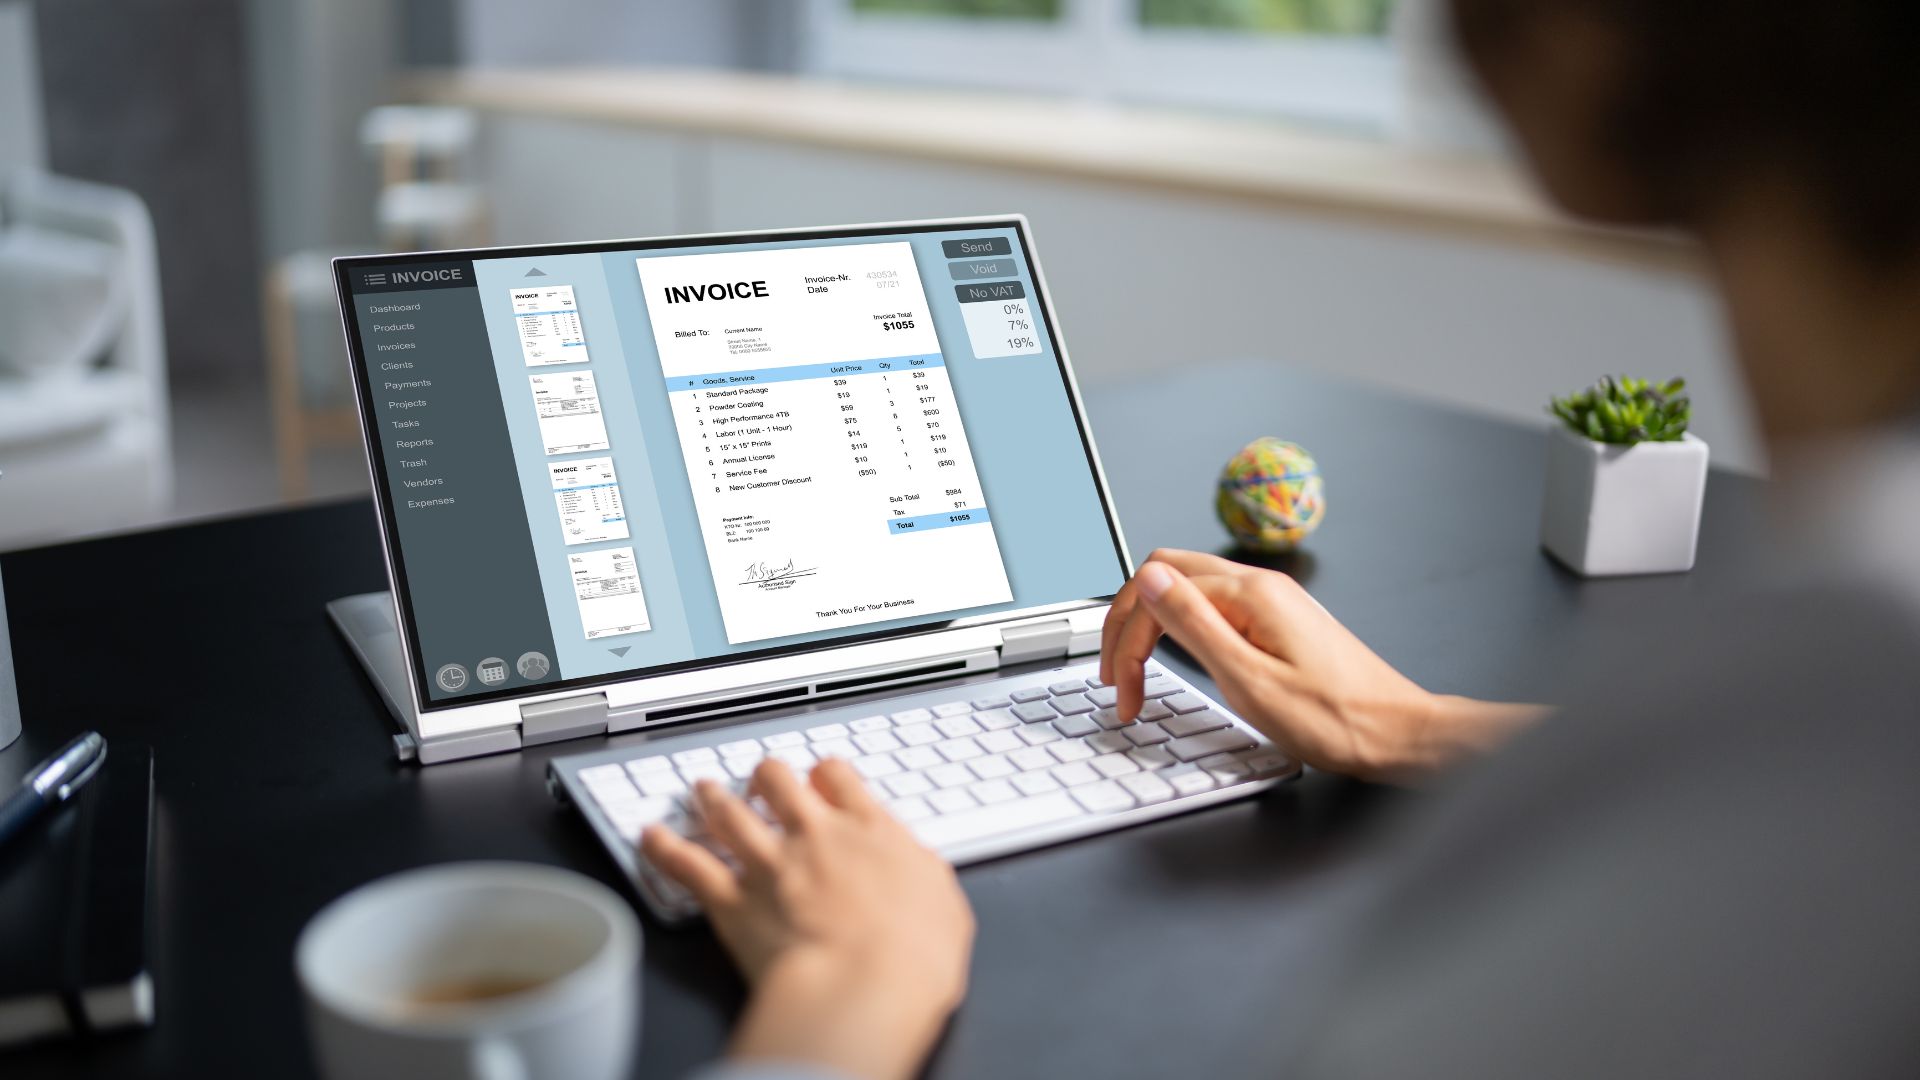
A customer who places several orders in a month does not always need a separate invoice for every transaction. Where the commercial arrangement and applicable tax rules allow it, those transactions can instead be grouped into a single consolidated invoice.
For businesses with repeat customers, this can reduce the number of billing documents finance teams have to create, send, track, and reconcile. The underlying transactions still need to remain clear and traceable, though. This guide explains what a consolidated invoice is, how consolidated invoicing works, when it makes sense, and how tax invoices require additional consideration.
A consolidated invoice is a single invoice that groups multiple transactions, orders, deliveries, services, or other billable items for the same customer over a defined billing period.
For example, suppose a customer places five orders during one month. Under transaction-by-transaction billing, the supplier could issue five separate invoices. With consolidated invoicing, those eligible orders can instead be brought together into one invoice showing the individual charges and the total amount payable.
The billing period does not have to be monthly. Depending on the commercial arrangement, a business might consolidate transactions weekly or according to another agreed billing cycle.
The important point is that consolidation should not make the underlying activity difficult to understand. The customer and the supplier's finance team should still be able to trace the invoice back to the transactions that created it.
Although the exact process depends on the business and its systems, consolidated billing normally follows a straightforward flow.
The business first records the individual billable events. These could include sales orders, deliveries, completed services, recurring charges, or other transactions.
Each transaction should retain the information needed for subsequent billing, such as the customer, date, items or services supplied, quantity, value, and relevant reference numbers.
Transactions belonging to the same customer are identified for the relevant billing period.
Not every open transaction necessarily belongs on the same invoice. Payment terms, contracts, purchase orders, tax treatment, customer requirements, and other conditions may require some items to remain separate.
The eligible transactions are combined into one billing document.
The invoice should retain enough detail for the customer to understand what is being charged. Depending on the business, this might include individual sales-order numbers, delivery references, service periods, line items, quantities, and values.
Instead of receiving several independent billing documents, the customer receives one invoice covering the consolidated transactions and a total amount due.
Once payment is received, the finance team records it against the consolidated invoice and maintains the connection between that invoice and its underlying transactions.
In simple terms:
Transactions → Group by customer and period → Generate one invoice → Receive payment → Reconcile
A standard invoice and a consolidated invoice serve the same basic commercial purpose: they document an amount a customer needs to pay. The difference lies mainly in how the underlying transactions are grouped.
A business might prefer separate invoices when every purchase order requires independent approval, projects have different payment terms, or customers want invoices issued immediately after each transaction.
Consolidated invoicing is more useful when grouping related transactions reduces unnecessary administration without creating confusion around payment, tax, or reconciliation.
A consolidated tax invoice generally refers to a tax invoice covering multiple qualifying taxable transactions rather than one individual supply. However, this is where businesses need to separate a general invoicing practice from a legal tax concept.
The rules governing tax invoices are jurisdiction-specific. A country may use terminology such as summary tax invoice, impose a maximum consolidation period, prescribe mandatory invoice fields, or restrict which transactions can be included.
A business should therefore not assume that because its accounting software can combine several charges into one document, that document automatically satisfies the applicable tax-invoice rules.
The distinction is useful:
Consolidated invoice: A commercial billing method in which several transactions are grouped into one invoice.
Consolidated or summary tax invoice: An invoice covering multiple supplies under conditions established by the applicable tax legislation.
The first is primarily an operational decision. The second can carry specific statutory requirements.
Saudi Arabia provides a useful example because its VAT rules expressly address summary tax invoices.
Under Article 53 of ZATCA's VAT Implementing Regulations, a taxable person may, in the circumstances covered by the relevant provision, issue a summary tax invoice containing more than one separate supply of goods or services to the same customer over a period not exceeding one calendar month.
The regulation also requires the summary tax invoice to contain the applicable minimum tax-invoice information and states that it must be issued no later than the fifteenth day of the month following the month to which the invoice relates.
Businesses operating in Saudi Arabia should review the current ZATCA VAT Implementing Regulations for the complete requirements rather than treating consolidation as a general exemption from normal invoicing rules.
HAL's guide to VAT invoices in Saudi Arabia provides additional context on standard and simplified tax invoices, invoice information, and Saudi e-invoicing requirements.
For businesses outside Saudi Arabia, the applicable local tax rules should determine whether transactions can be combined and what the resulting tax invoice must contain.
There is no single universal consolidated-invoice format. The required information depends partly on the business arrangement and, where the document is a tax invoice, the applicable jurisdiction.
For commercial clarity, a consolidated invoice will commonly need information such as:
Transaction references are particularly important. Reducing five invoices to one is useful only if the customer can still determine what each charge relates to.
For tax invoices, businesses should use the mandatory fields prescribed by the relevant tax authority rather than relying on a generic invoice template.
The main advantages of consolidated invoicing are operational. They become more noticeable as transaction frequency grows.
If the same customer places several orders every month, issuing one invoice per order can create a large document volume.
Consolidating eligible transactions can reduce the number of invoices finance teams need to generate, review, send, and monitor.
Consolidation can also reduce administrative work on the customer's side.
Instead of receiving several payment requests from the same supplier during a billing period, the accounts payable team can work with one document covering the relevant transactions.
A consolidated invoice brings multiple charges under one billing document and, where appropriate, one payment obligation.
That can make it easier for both parties to see what remains outstanding without tracking several invoice numbers and due amounts separately.
A properly itemized consolidated invoice gives the customer a single view of activity during the billing period.
Finance teams can see both the combined account value and the transactions contributing to it.
Consolidation can simplify reconciliation when the billing system preserves the relationship between the consolidated invoice and the underlying orders or transactions.
Without that traceability, however, consolidation can create the opposite problem: one large balance that is difficult to investigate when a customer disputes an individual charge.
Consolidated invoicing works best when it solves a genuine billing problem rather than simply reducing the number of documents.
It can be useful when:
Separate invoicing may be more appropriate when:
Customer expectations matter too. A billing method that makes internal processing easier but creates extra reconciliation work for the customer may not be an improvement.
Consider a trading business that supplies the same customer four times during one month:
With separate billing, the supplier could issue four invoices.
With consolidated billing, the eligible orders could instead appear on one invoice, with each order reference and value shown separately and SAR 20,000 presented as the combined pre-tax value.
Whether those transactions may also be combined into one tax invoice is a separate question. The supplier would need to apply the invoicing, timing, VAT, and e-invoicing rules relevant to the transaction and jurisdiction.
This distinction is important: commercial consolidation should never be used to bypass tax-invoice requirements.
Consolidation becomes harder to manage manually as the number of customers, sales orders, line items, adjustments, payments, and billing cycles increases.
An integrated invoicing system can help maintain the connection between the original transaction and the invoice produced from it.
HAL Invoicing supports invoicing workflows connected with sales orders and other business documents, alongside payment management, invoice-status visibility, accounting information, and configurable tax rules.
HAL's support documentation also describes a multiple-sales-order invoicing workflow in which multiple sales orders for the same customer can be selected to create a single invoice.
That operational capability should still be kept separate from tax interpretation. The business remains responsible for determining whether the underlying transactions can legally be consolidated into a particular tax invoice and for applying the relevant jurisdiction's requirements.
Consolidated invoicing can make repeat-customer billing easier by bringing several eligible transactions into one clear, traceable document. The goal is not simply to issue fewer invoices, but to simplify billing without losing transaction detail or creating reconciliation problems.
Tax treatment requires additional care because the rules for summary or consolidated tax invoices vary by jurisdiction.
For businesses handling growing sales and invoice volumes, HAL Invoicing connects invoicing with wider sales, payment, and accounting workflows. Book a HAL demo to explore how the platform can support your billing processes.
A consolidated invoice is one billing document that combines multiple eligible transactions, orders, services, deliveries, or other charges for the same customer. It allows the customer to receive and pay one invoice while retaining details of the transactions included within it.
A consolidated tax invoice is generally a tax invoice containing multiple qualifying taxable transactions. Its precise legal meaning depends on the jurisdiction. Tax authorities may impose rules covering eligible transactions, consolidation periods, invoice contents, issuance deadlines, and electronic invoicing.
A regular invoice commonly covers an individual transaction or billing event. A consolidated invoice groups multiple eligible transactions into one document. Both should provide enough information for the customer and supplier to understand and reconcile the amount being billed.
Yes, multiple orders can be included in a single invoice when the business's billing process, customer arrangement, and applicable tax rules permit it. HAL's invoicing documentation, for example, describes creating one invoice from multiple sales orders belonging to the same customer.
It is most useful when the same customer generates several transactions during a billing period and separate invoices create unnecessary administrative work. Businesses should still consider customer preferences, payment terms, contractual requirements, tax treatment, and the need to trace individual transactions.
Recurring invoicing generates invoices repeatedly according to a schedule, often for an ongoing service or subscription.
Consolidated invoicing combines several transactions or charges into one invoice. An invoice can therefore be recurring without being consolidated, while a consolidated invoice can contain transactions that are not themselves recurring.