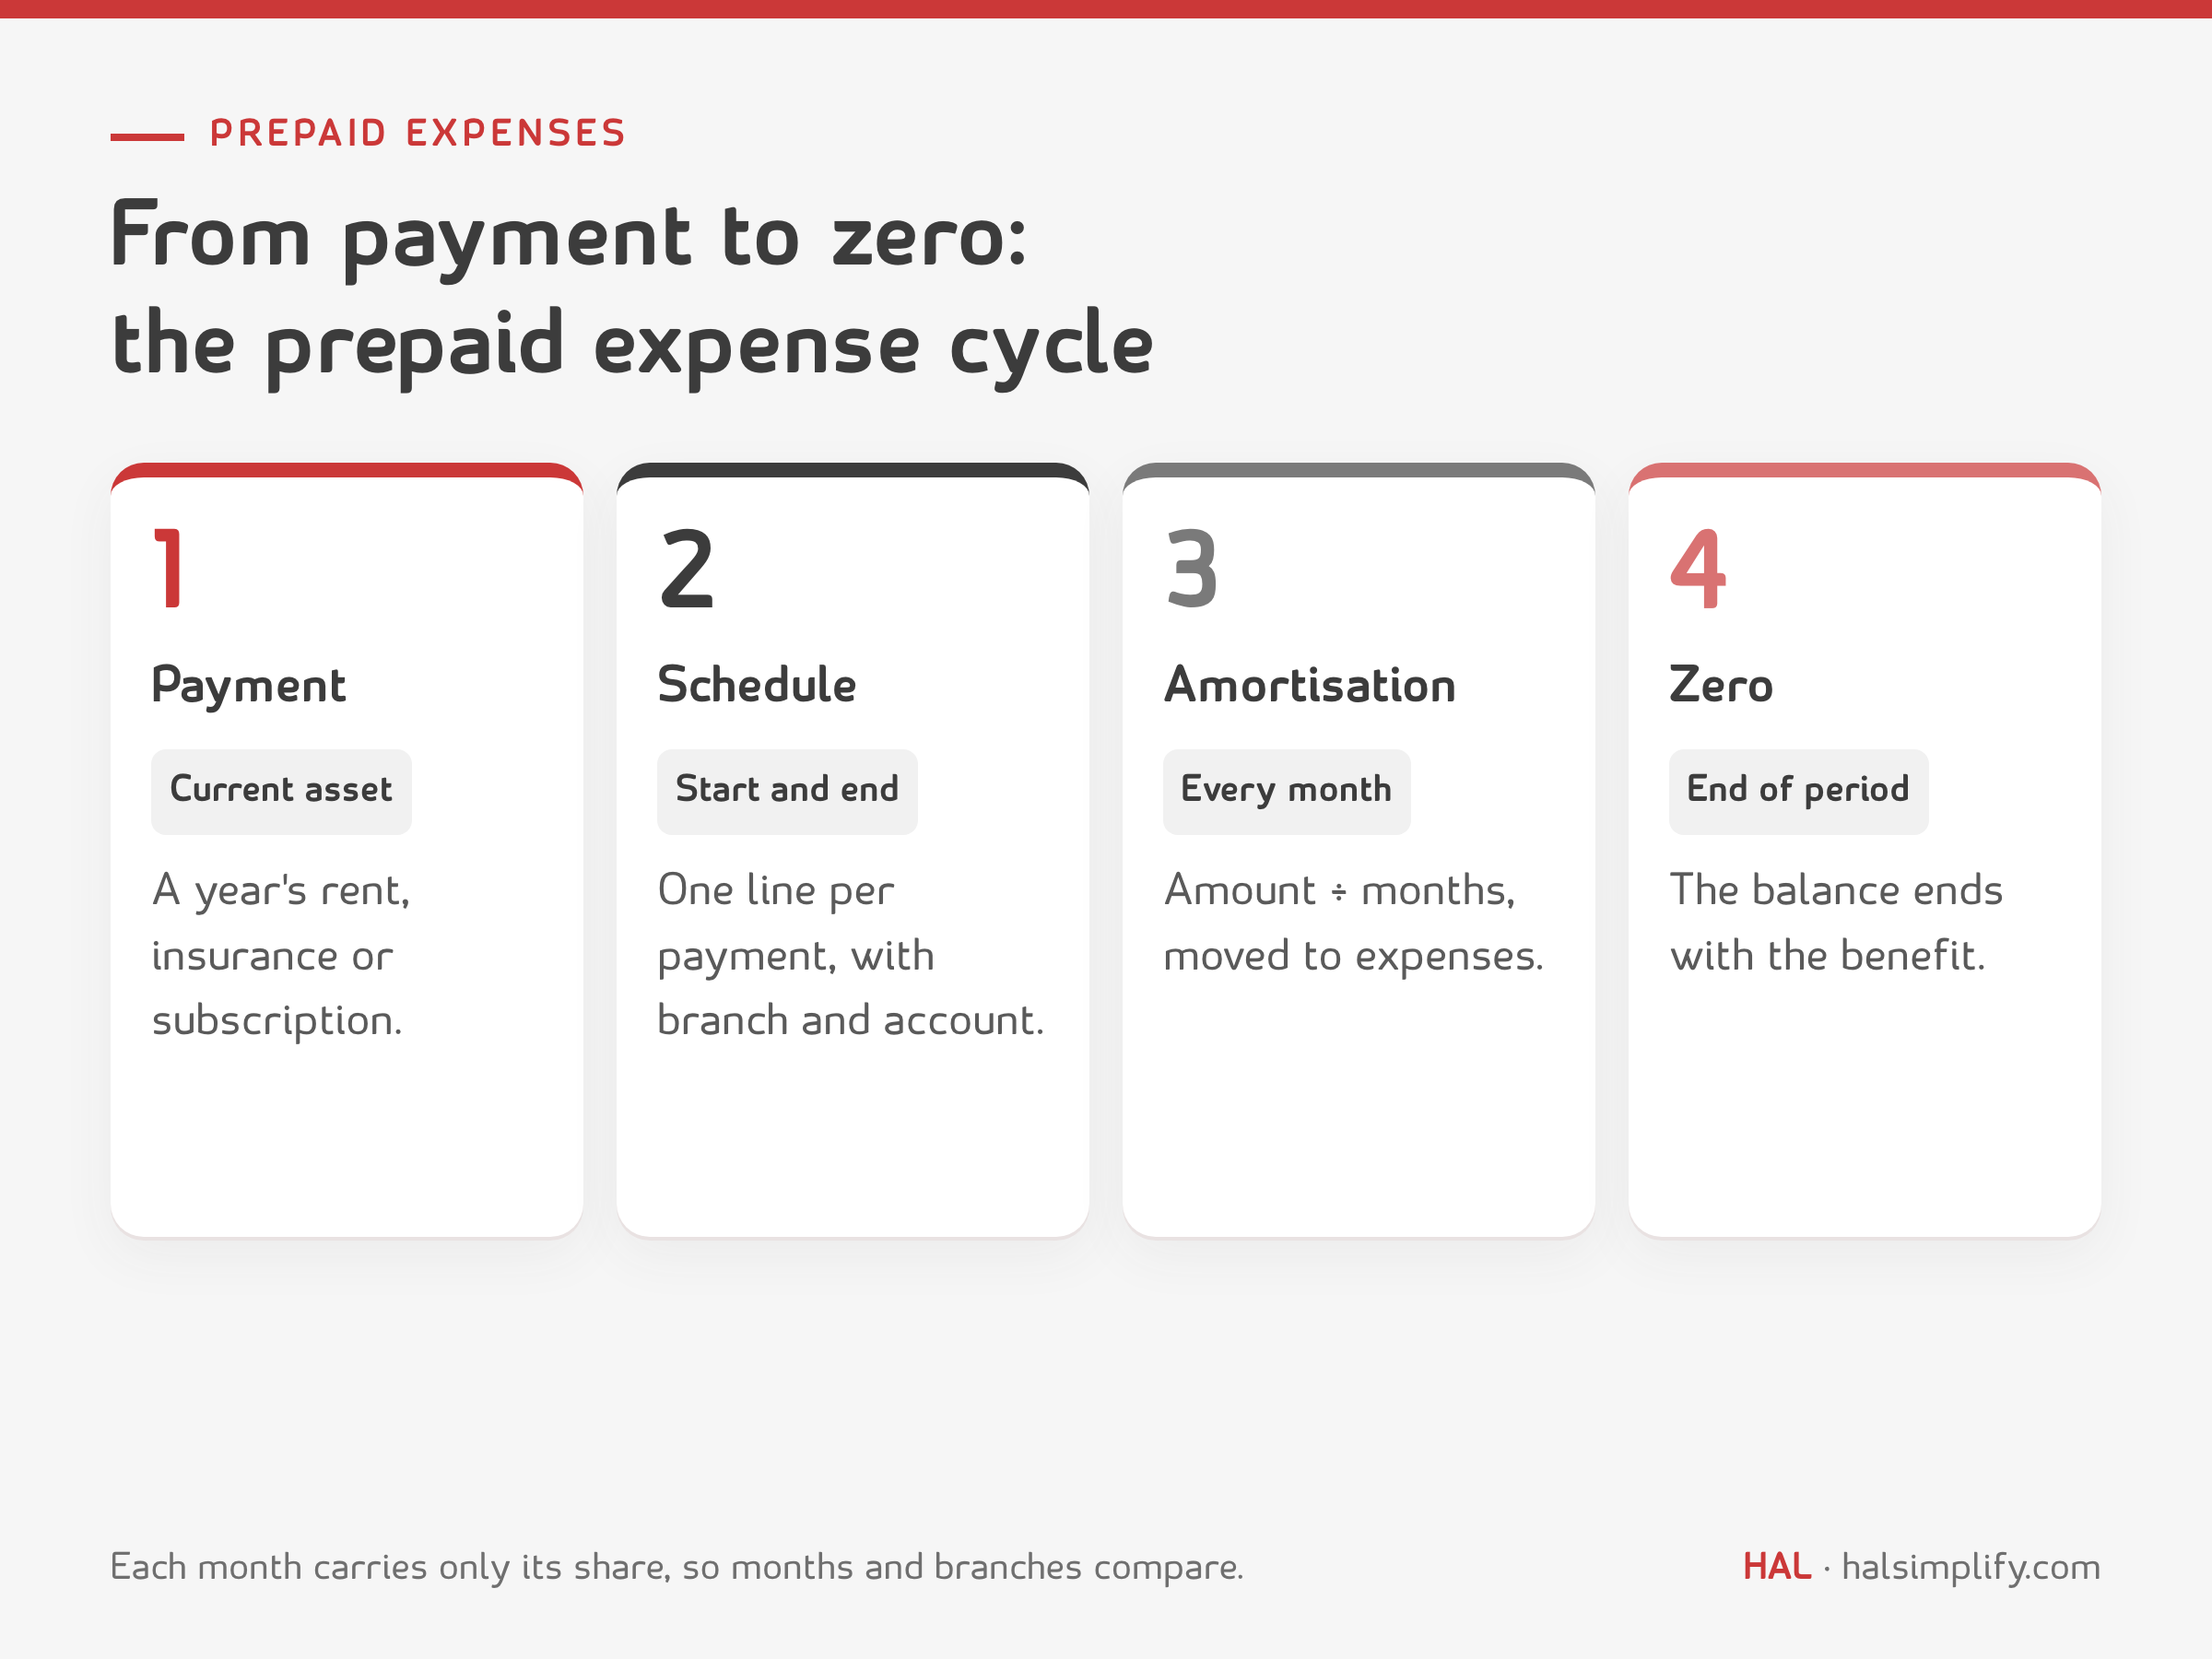
In short: Prepaid expenses are amounts a business pays today for a benefit it receives in coming months, such as a year's branch rent, an annual insurance policy or an annual software subscription. They are recorded as a current asset when paid, and a portion is moved to expenses each month (amortisation) until the balance runs out at the end of the period. This guide covers the journal entries, what counts as a prepaid expense and what doesn't, VAT treatment in Saudi Arabia, a restaurant group example with three branches, and a free Excel schedule that works out the amortisation and the entries each month.
Month-end at a restaurant group with three branches. The finance manager opens the income statement and finds that the Dammam branch lost more than SAR 200,000 in October, even though its sales were normal. The kitchen isn't the problem, and neither is the dining room: the whole year's rent (SAR 216,000) was booked as an expense in the month it was paid. For the next eleven months the branch will look more profitable than it is, because it will carry no rent at all.
That is the error prepaid expense accounting prevents: each month carries only its own share of the cost, so branches and months can be compared. This guide walks through the method step by step, with examples from the Saudi market.
A prepaid expense is an amount paid (or payable) before the business receives the service or benefit. Because the benefit hasn't been used yet, on the payment date the amount is an asset, not an expense: the business has a right to a future service. As each month passes, part of that right is used up, and the used part moves from the asset to expenses. This applies the accrual principle of matching an expense to the period it belongs to, and it is the mirror image of accrued expenses, where the benefit is used first and paid for later.
Prepaid expenses sit in the balance sheet under current assets when the benefit ends within a year; any part that runs beyond a year is non-current.
| Item | Prepaid expense? | Treatment |
|---|---|---|
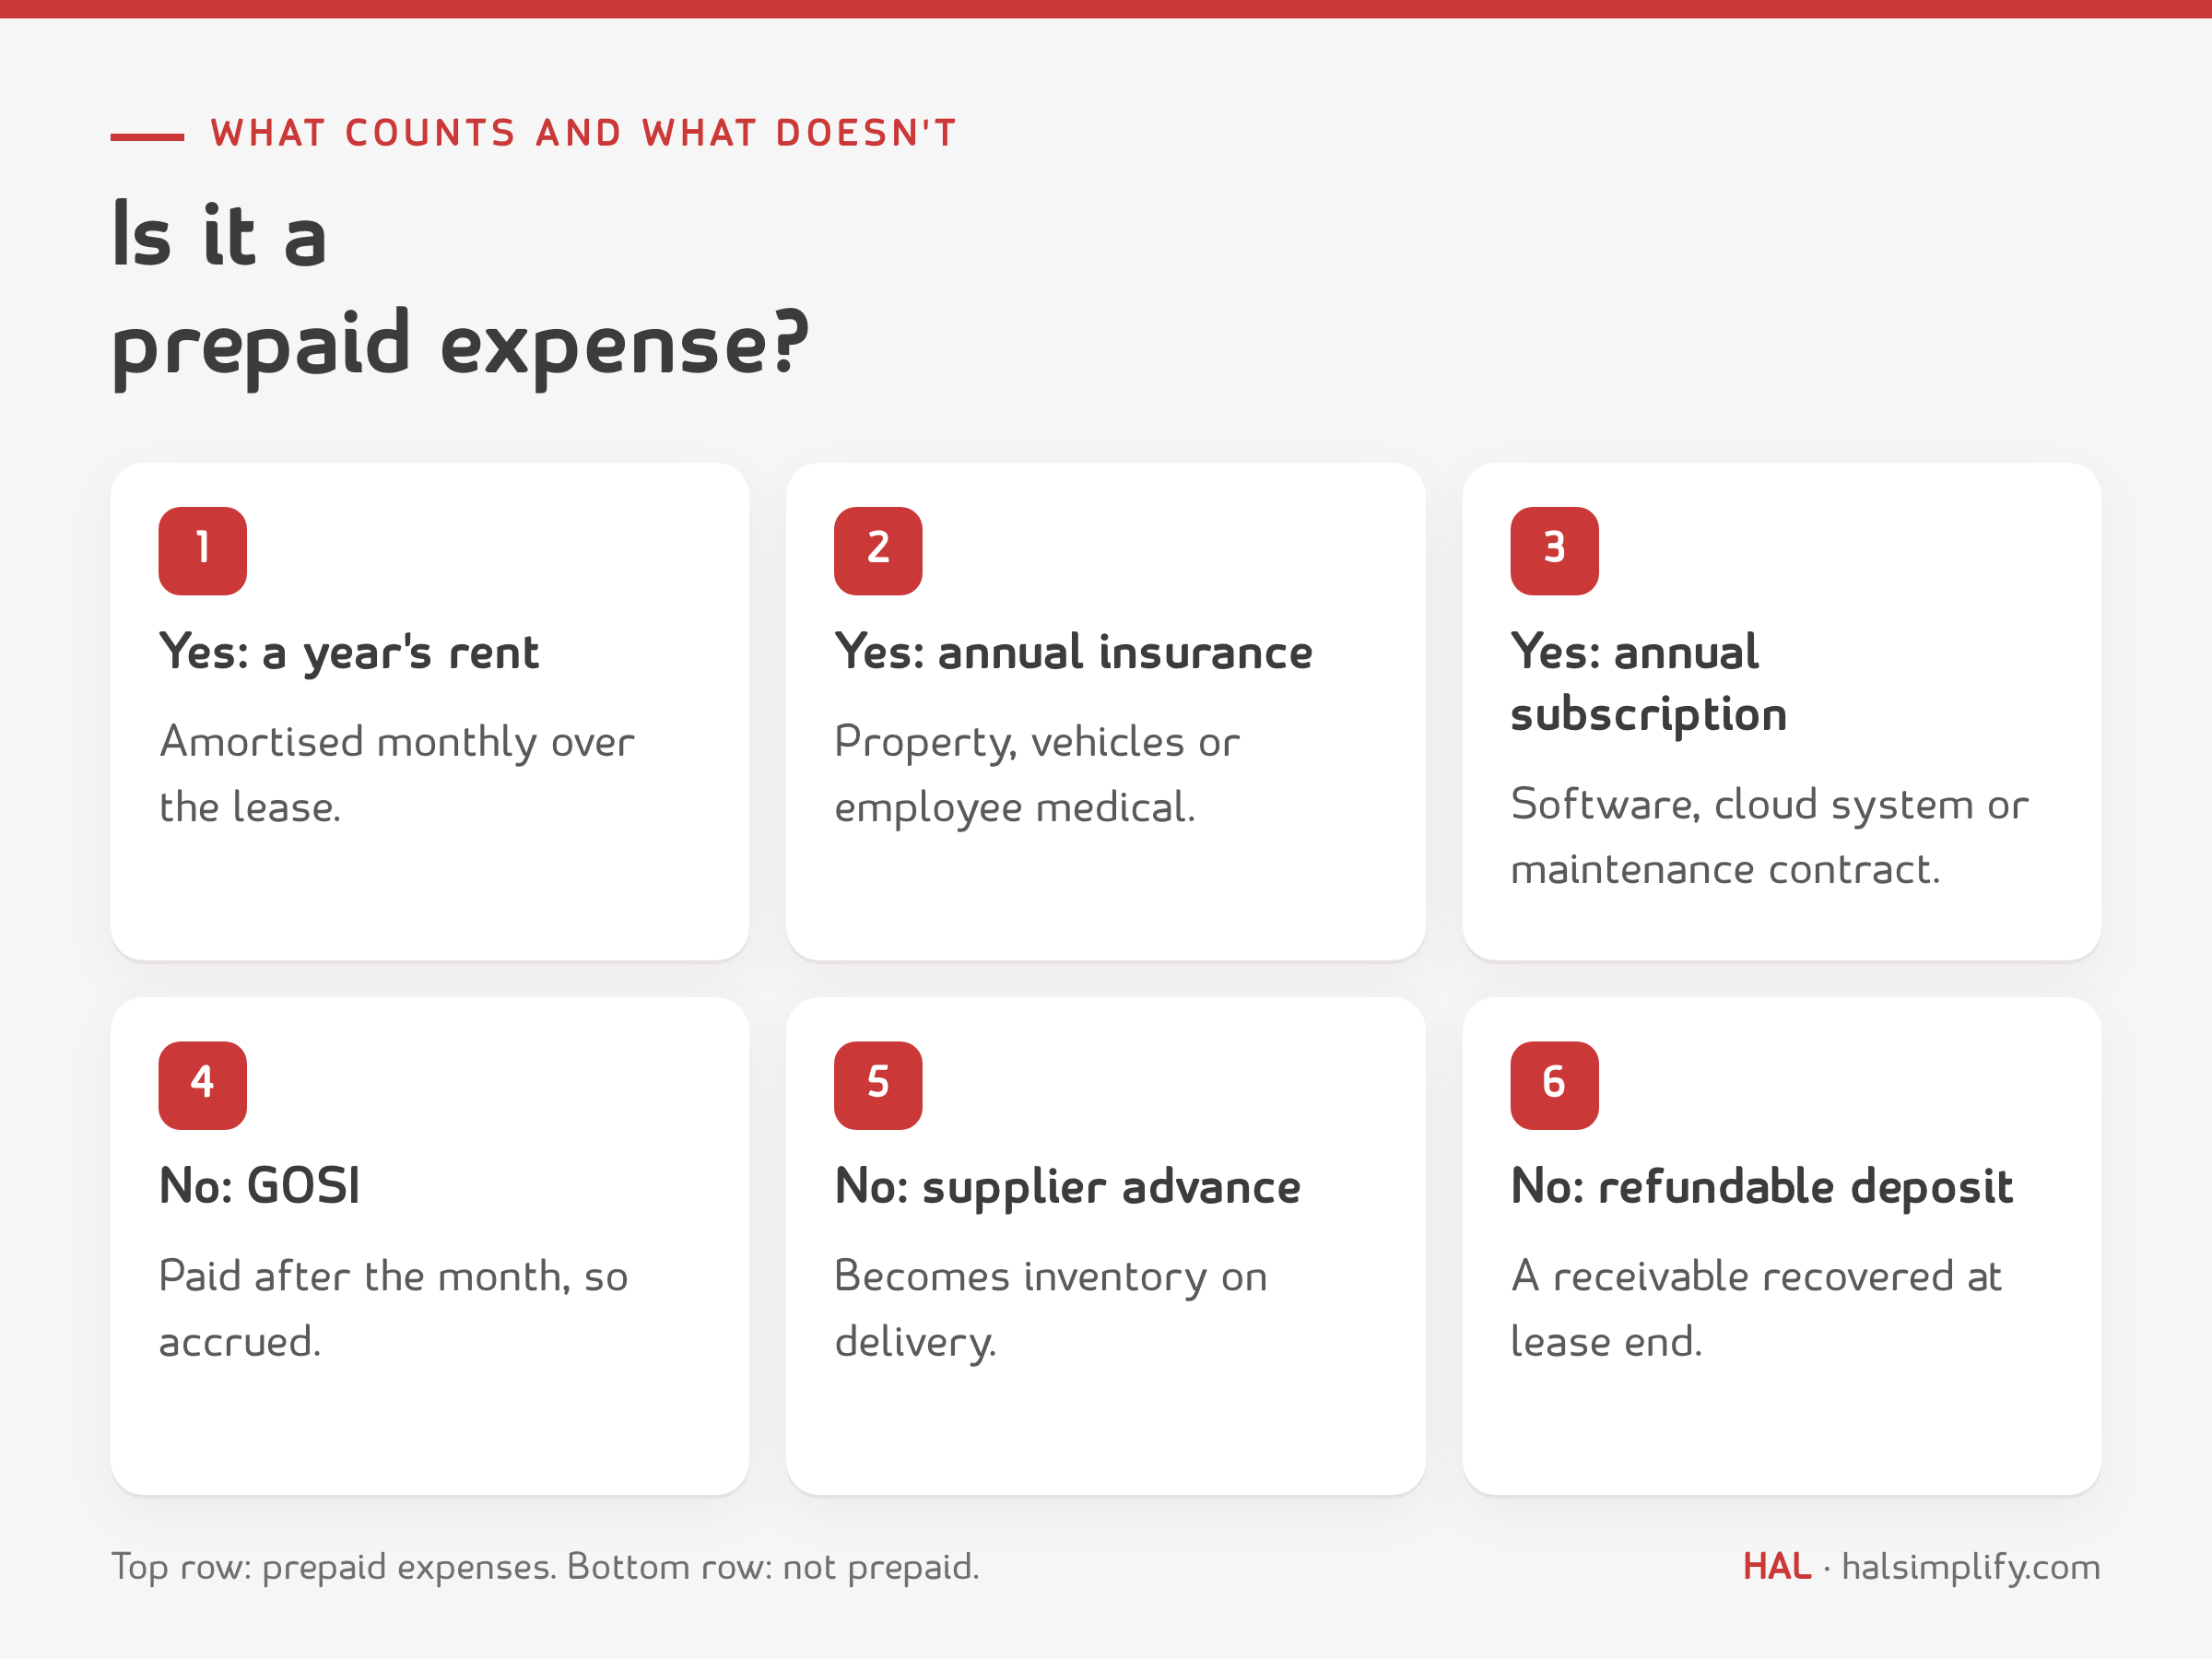
| Rent for a branch or warehouse on a one-year lease paid upfront | Usually yes (see the note below) | Amortised monthly over the lease term |
| Annual insurance policy (property, vehicles, employee medical) | Yes | Premium amortised over the policy months |
| Annual subscription to software or a cloud system | Yes | Amortised over the subscription months |
| Annual maintenance contract paid upfront | Yes | Amortised over the contract term |
| GOSI social insurance contributions | No | Calculated on the month's wages and paid after it, so accrued at month-end, not prepaid |
| Advance to a food or materials supplier before delivery | No | An advance to a supplier; becomes inventory on receipt |
| Refundable security deposit to the landlord | No | A receivable recovered at the end of the lease; not amortised |
A note on rent. Most unlisted Saudi companies apply the IFRS for SMEs Standard as endorsed in the Kingdom. Under it, operating lease rent is expensed on a straight-line basis over the lease term, so the part paid in advance is a prepaid expense. Companies that apply full IFRS (IFRS 16) record leases longer than 12 months as a right-of-use asset and a lease liability; only short-term leases (12 months or less) stay in prepaid expenses, and only if the company elects the exemption. Ask your auditor which framework your company applies.
A note on GOSI. Social insurance contributions are calculated on the same month's wages, and GOSI asks employers to pay them within the first fifteen days of the following month. So they are recorded at each month-end as an expense with an accrued liability, not as a prepaid expense.
Two entries: one when you pay, and one every month:
| When | Debit | Credit |
|---|---|---|
| On payment | Prepaid expenses (amount before VAT) + input VAT | Bank |
| Each month-end (amortisation) | Rent, insurance or subscription expense (for the branch or cost centre) | Prepaid expenses |
Monthly amortisation = amount before VAT ÷ number of months of benefit. If the period starts mid-month, either prorate the first month by days or set a company policy of starting from the following month, and apply it consistently.
To keep the numbers right, keep a prepaid expense schedule: one line per payment with the supplier, branch, expense account, start and end dates, amount, monthly charge and remaining balance. The total of the remaining balances must equal the prepaid account in the general ledger every month.
A restaurant group (fictitious) has three branches, each on a 12-month commercial lease paid upfront. The landlords are VAT-registered, and the group applies the IFRS for SMEs Standard.
| Branch | Lease term | Annual rent before VAT | VAT 15% | Paid to landlord | Monthly amortisation |
|---|---|---|---|---|---|
| Riyadh | 1 Jul 2026 to 30 Jun 2027 | 360,000 | 54,000 | 414,000 | 30,000 |
| Jeddah | 1 Sep 2026 to 31 Aug 2027 | 288,000 | 43,200 | 331,200 | 24,000 |
| Dammam | 1 Nov 2026 to 31 Oct 2027 | 216,000 | 32,400 | 248,400 | 18,000 |
| Total | 864,000 | 129,600 | 993,600 | 72,000 |
Payment entry for the Dammam rent (paid on 29 October 2026 against the tax invoice):
| Account | Debit | Credit |
|---|---|---|
| Prepaid rent: Dammam branch | 216,000 | |
| Input VAT | 32,400 | |
| Bank | 248,400 |
Nothing from the Dammam rent is charged to October, because the lease starts in November. That alone removes the phantom loss we started with.
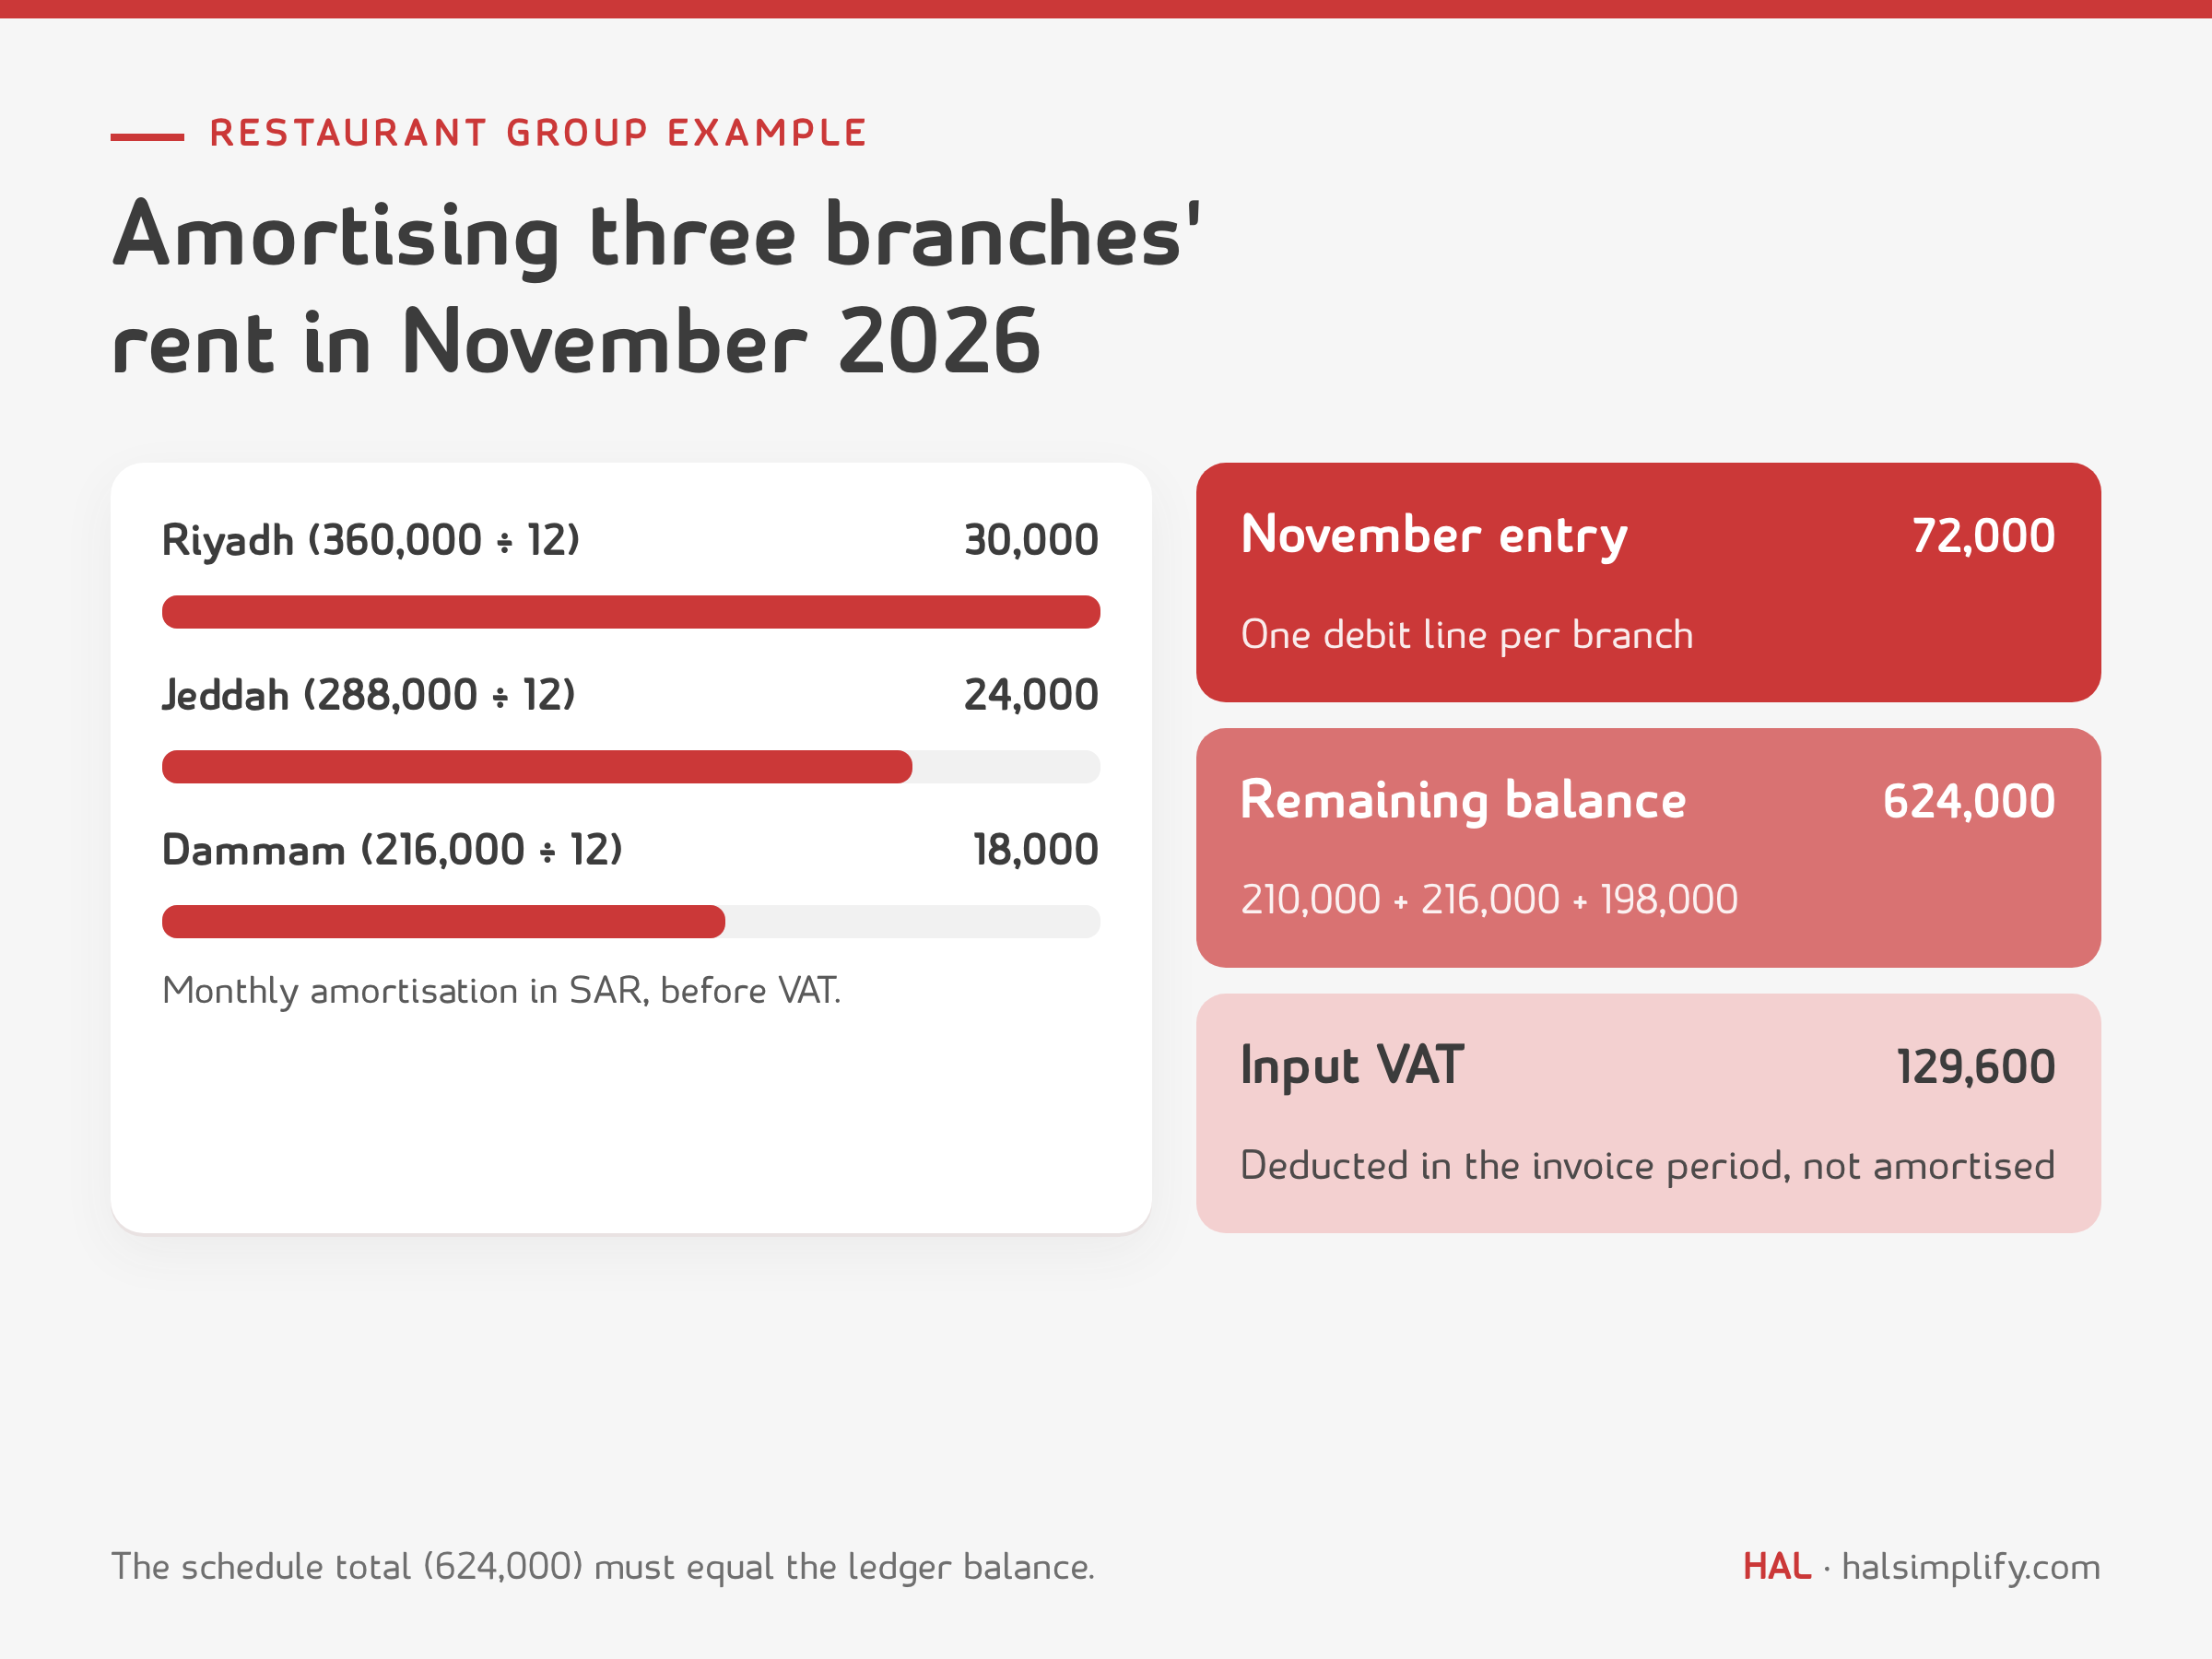
November 2026 amortisation entry (one line per branch, so rent shows in the right branch's profit):
| Account | Debit | Credit |
|---|---|---|
| Rent expense: Riyadh branch | 30,000 | |
| Rent expense: Jeddah branch | 24,000 | |
| Rent expense: Dammam branch | 18,000 | |
| Prepaid rent | 72,000 |
Remaining balance at 30 November 2026: Riyadh SAR 210,000 (after 5 of 12 months), Jeddah SAR 216,000 (after 3 months), Dammam SAR 198,000 (after one month). The total, SAR 624,000, must equal the prepaid rent account in the general ledger.
The Excel workbook in the kit is pre-filled with this example, plus an annual software subscription, a property insurance policy and a maintenance contract paid in November that starts in December, so you can see how it handles each case. If your group keeps these schedules by hand for each branch, see HAL pricing or book a demo.
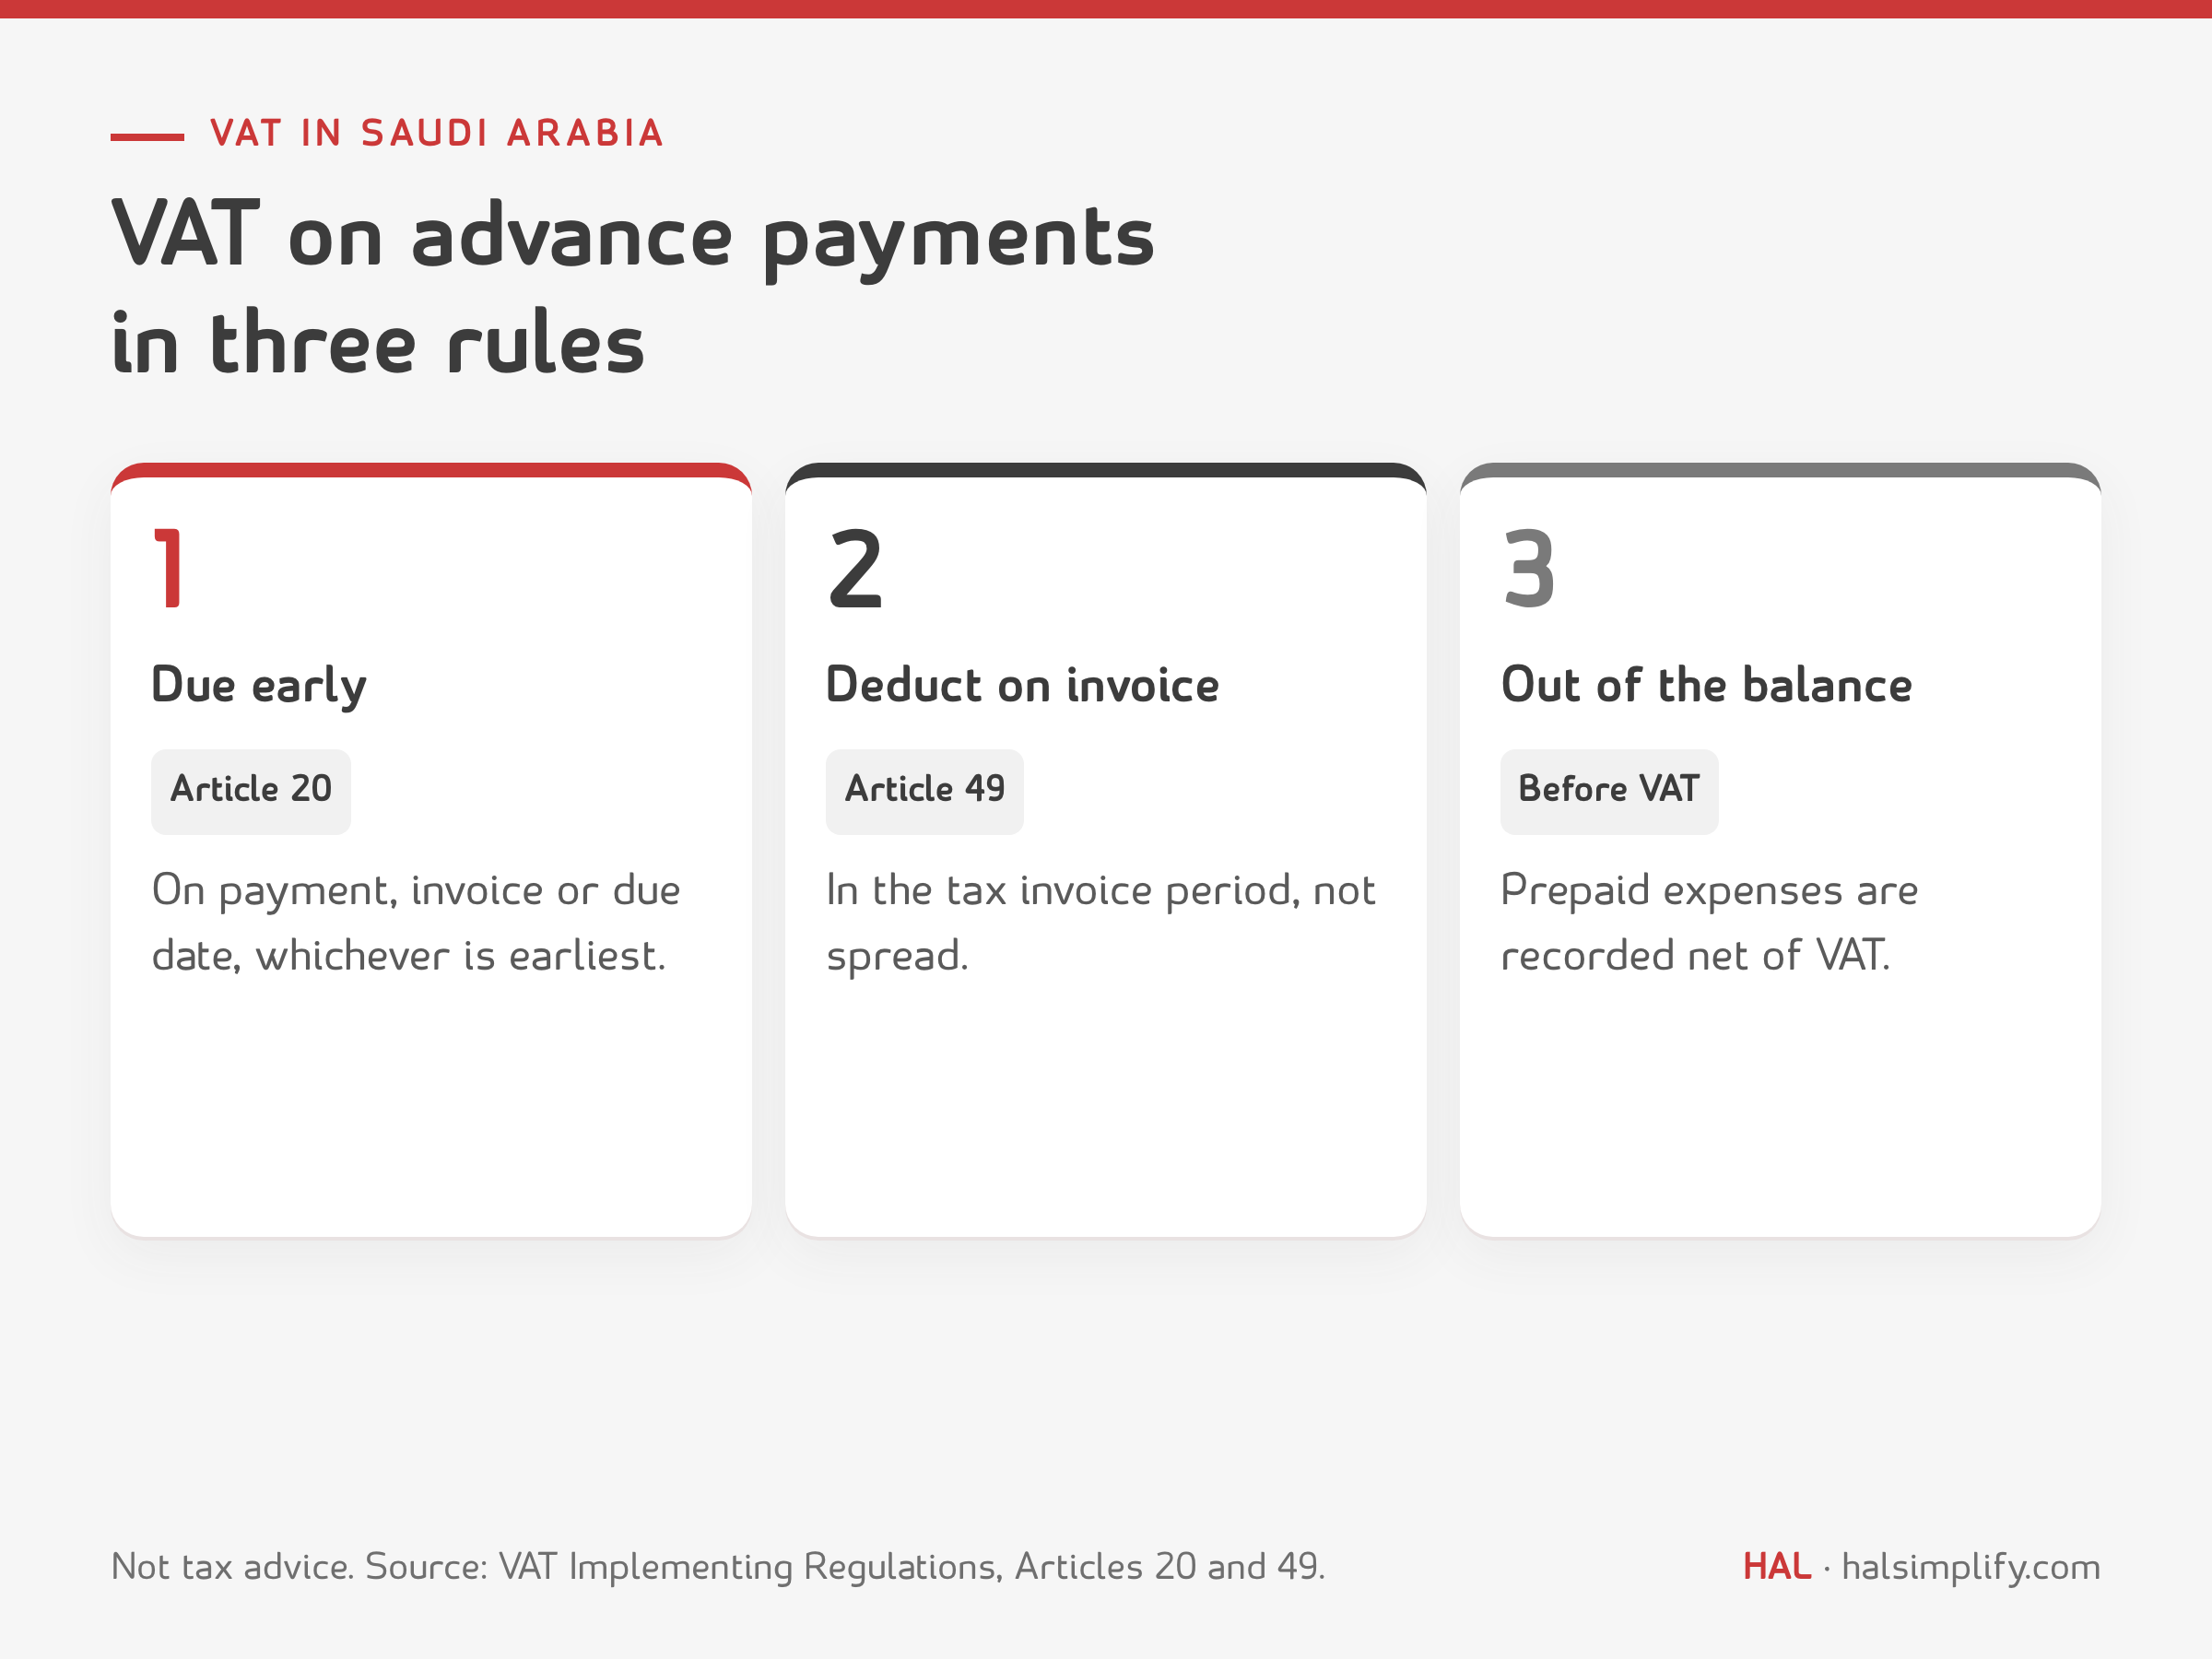
These are general points from the text of the Regulations, not tax advice. Check special cases with your tax adviser.
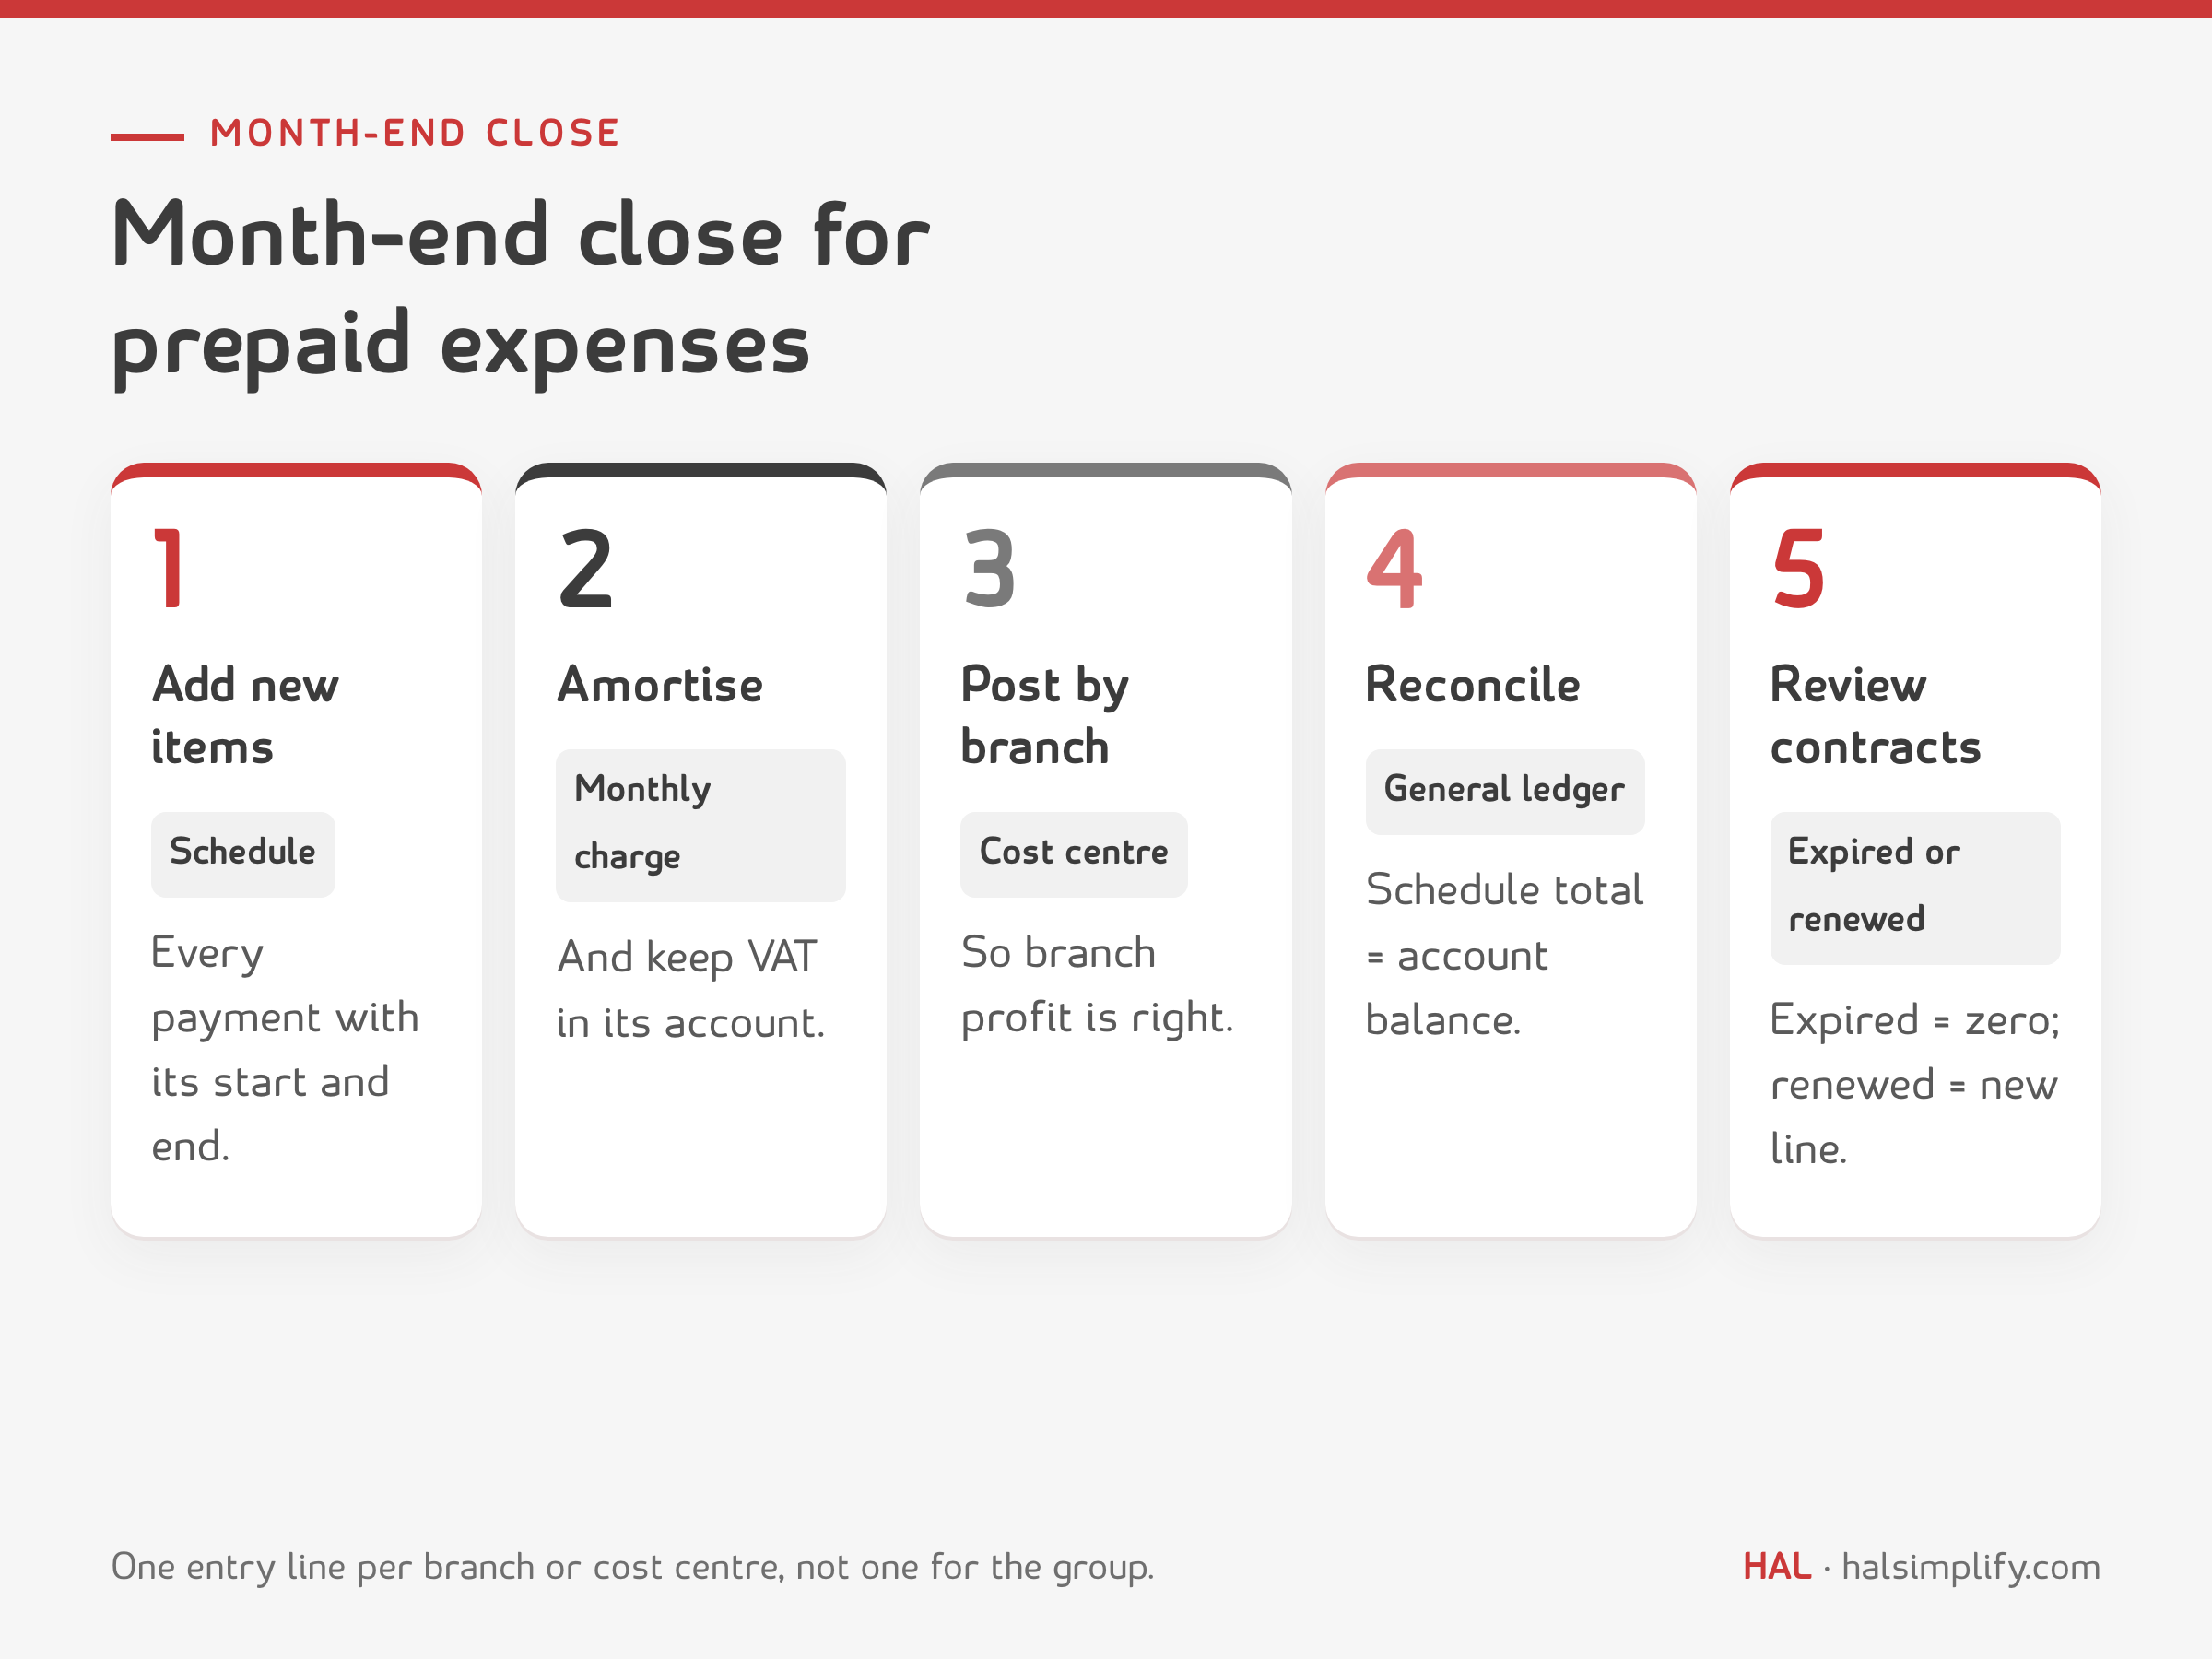
This checklist is part of the full month-end close, covered in the month-end closing process, which ends with the adjusted trial balance.
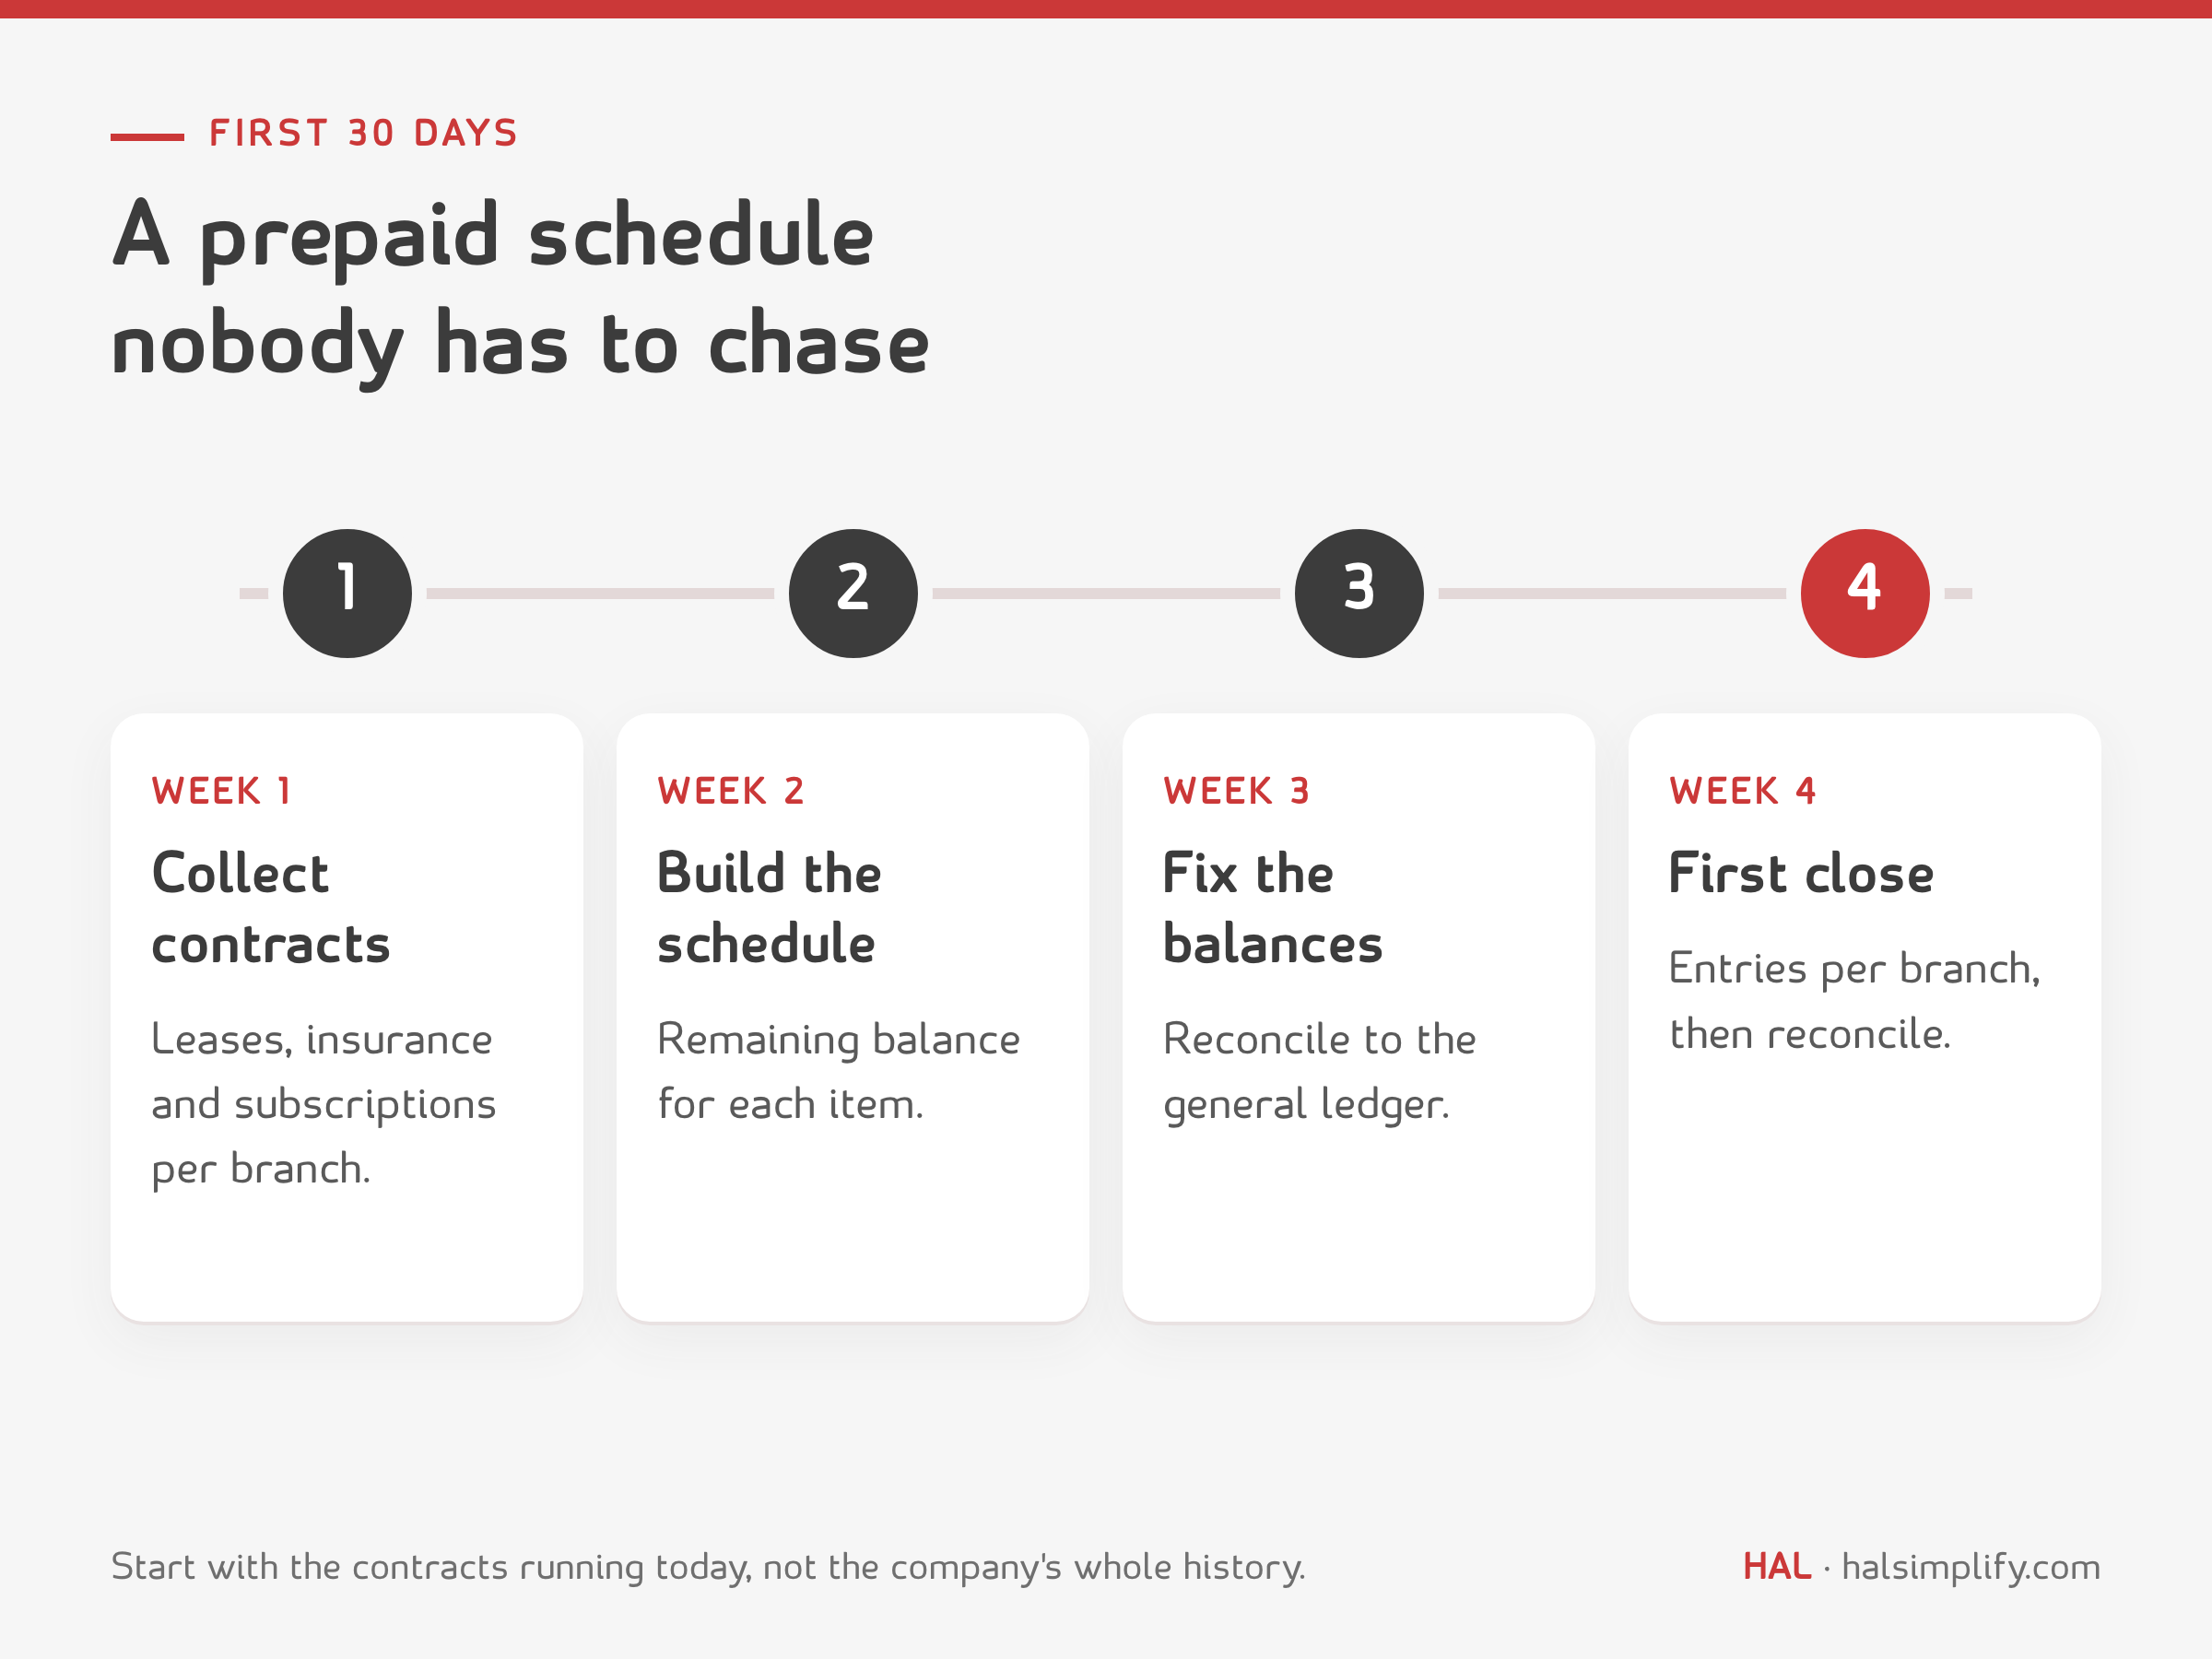
A ready-to-use kit with everything in this article:
A spreadsheet works for twenty items. As branches and contracts multiply, keying amortisation entries every month becomes repetitive work where a line is easily missed. In HAL accounting, journal entries are automated with complete control over ledgers, expenses, journals and transfers can be processed in bulk, VAT reports are ready to file, and bank reconciliation is simpler. HAL connects to POS systems such as Foodics or Micros, and the HAL POSsible point of sale lets you see sales across all outlets in one place, so you read each branch's profit after it carries its right share of rent.
Amounts paid today for a benefit in coming months, such as a year's rent, annual insurance or an annual subscription. They are recorded as a current asset when paid, and a portion is charged to expenses each month until the balance runs out.
On payment: debit prepaid expenses (amount before VAT) and input VAT, credit bank. At each month-end: debit the related expense (rent or insurance), credit prepaid expenses with the month's share.
No. GOSI social insurance contributions are calculated on the month's wages and paid after it, so they are recorded at month-end as an expense with an accrued liability.
For companies applying the IFRS for SMEs Standard, yes, and it is amortised on a straight-line basis. For companies applying IFRS 16, leases longer than 12 months are recorded as a right-of-use asset and a lease liability, and only short-term leases stay in prepaid expenses if the company elects the exemption.
Input VAT is deducted in the period of the tax invoice, not spread over the amortisation months. Only the amount before VAT is recorded in prepaid expenses.
Yes. The kit is free: a PDF guide with printable forms and an Excel workbook that works out the monthly amortisation and remaining balance and prepares the month's entries per branch.