Construction billing determines how a contractor calculates what a customer owes, when invoices are issued, and what evidence supports each payment claim.
The right structure depends on the contract. A fixed-price project may use progress invoices, while another project may bill actual labour and materials. Retention, advance payments, change orders, and VAT can then affect the amount billed or collected at each stage.
For Saudi contractors, the billing process must also account for the Kingdom’s 15% VAT rules for construction and contracting services, including specific treatment for progress claims, advance payments, retention, and certain government contracts.
This guide explains six common construction billing methods, when each works best, their advantages and risks, and the Saudi billing and VAT rules contractors should consider before issuing an invoice.
For related project-cost controls, see HAL’s Construction Cost Management guide.
Construction billing is the process of calculating, documenting, invoicing, and collecting amounts due under a construction contract.
Unlike simple product invoicing, a construction invoice may depend on:
In Saudi commercial practice, a construction completion or progress report may also be referred to as a Mustakhlas. ZATCA describes this as a document used to determine the amount payable for part of a construction project and obtain the customer’s approval. It is not automatically the same thing as the formal tax invoice.
These terms are often mixed together, but they answer different questions.
A project can therefore use more than one approach at the same time.
For example, a contractor may have a lump-sum contract but issue monthly progress invoices and have 5% retention withheld from each certified payment.
A structured billing process helps contractors:
The billing method should therefore follow the contract rather than being selected independently after work begins.

Construction projects often combine a pricing basis with a billing schedule. The six approaches below cover the most common ways project charges are calculated or invoiced.
Under a lump-sum contract, the contractor agrees to deliver the defined scope for an agreed total price.
The customer may still pay that price through several progress invoices rather than one invoice at completion.
Best suited for:
Advantages:
Risks:
Under time and materials billing, the customer is charged based on actual labour time and materials used, according to rates defined in the contract.
Best suited for:
Advantages:
Risks:
Under a cost-plus arrangement, the customer reimburses allowable project costs and pays the contractor an additional agreed fee.
That fee may be structured as a fixed amount, percentage, or another contractually defined basis.
Best suited for:
Advantages:
Risks:
Under unit-price billing, the parties agree a price for each measurable unit of work.
The amount billed is then based on:
Agreed unit price × verified quantity completed
Examples may include:
Best suited for:
Advantages:
Risks:
Progress billing allows the contractor to invoice portions of the contract value as work progresses.
Invoices may be based on:
ZATCA’s current contracting guidance recognizes that construction services are generally continuous supplies and that multiple invoices or interim payments can create separate VAT due dates during the project. (ZATCA Contracting Sector VAT Guideline)
Best suited for:
Advantages:
Risks:
HAL itself supports progressive invoicing, allowing a percentage of a sales-order amount to be invoiced progressively. (HAL Progressive Invoice documentation)
Advance billing occurs when the customer pays part of the contract amount before the related work is completed.
Construction contracts may use advances to support:
The advance is normally deducted from later progress claims according to the contract.
Advantages:
Risks:
Advance payments can create a VAT obligation before the related construction work is completed.
ZATCA’s current contracting guideline gives an example where a contractor receives a down payment for future construction work and must calculate VAT and issue a tax invoice for the amount received. (ZATCA Contracting Sector VAT Guideline)
The advance must then be accounted for correctly when subsequent progress invoices are prepared.
Construction and contracting services relating to real estate in Saudi Arabia are generally subject to VAT at the standard 15% rate. (ZATCA Contracting Sector VAT Guideline)
The billing method can affect when VAT becomes due, so finance teams should not treat invoicing and VAT as separate processes.
Construction services are generally treated as continuous supplies.
Depending on the contract, VAT can become due based on events such as:
ZATCA’s current guideline explains that individual interim payments or invoices can create separate VAT due dates during a construction project.
Retention does not automatically reduce VAT on an amount that has already been fully invoiced.
If the contractor issues a tax invoice for the full amount due, VAT is due on the full invoiced amount, even if the customer withholds part of the payment as retention.
When that retained balance is later released, ZATCA states that there is no separate obligation to issue another invoice or declare VAT again merely because the retained cash is paid. (ZATCA retention guidance)
For a worked example and invoice format, see HAL’s Retention Invoice Template for Saudi Arabia article.
Where an advance payment represents consideration for future taxable construction services, receipt of that payment can trigger VAT and a related tax-invoice requirement.
Certain supplies made directly to Saudi government entities under contracts governed by the Government Tenders and Procurement Law have special VAT timing rules.
For qualifying claims, VAT generally becomes due on the payment-order date or the date payment is received, whichever occurs earlier. The special treatment applies to the main contractor contracting directly with the government entity, not automatically to its subcontractors. (ZATCA guidance for government contractors)
Because billing structures can differ significantly between private, subcontract, and government projects, tax treatment should be reviewed against the actual contract.
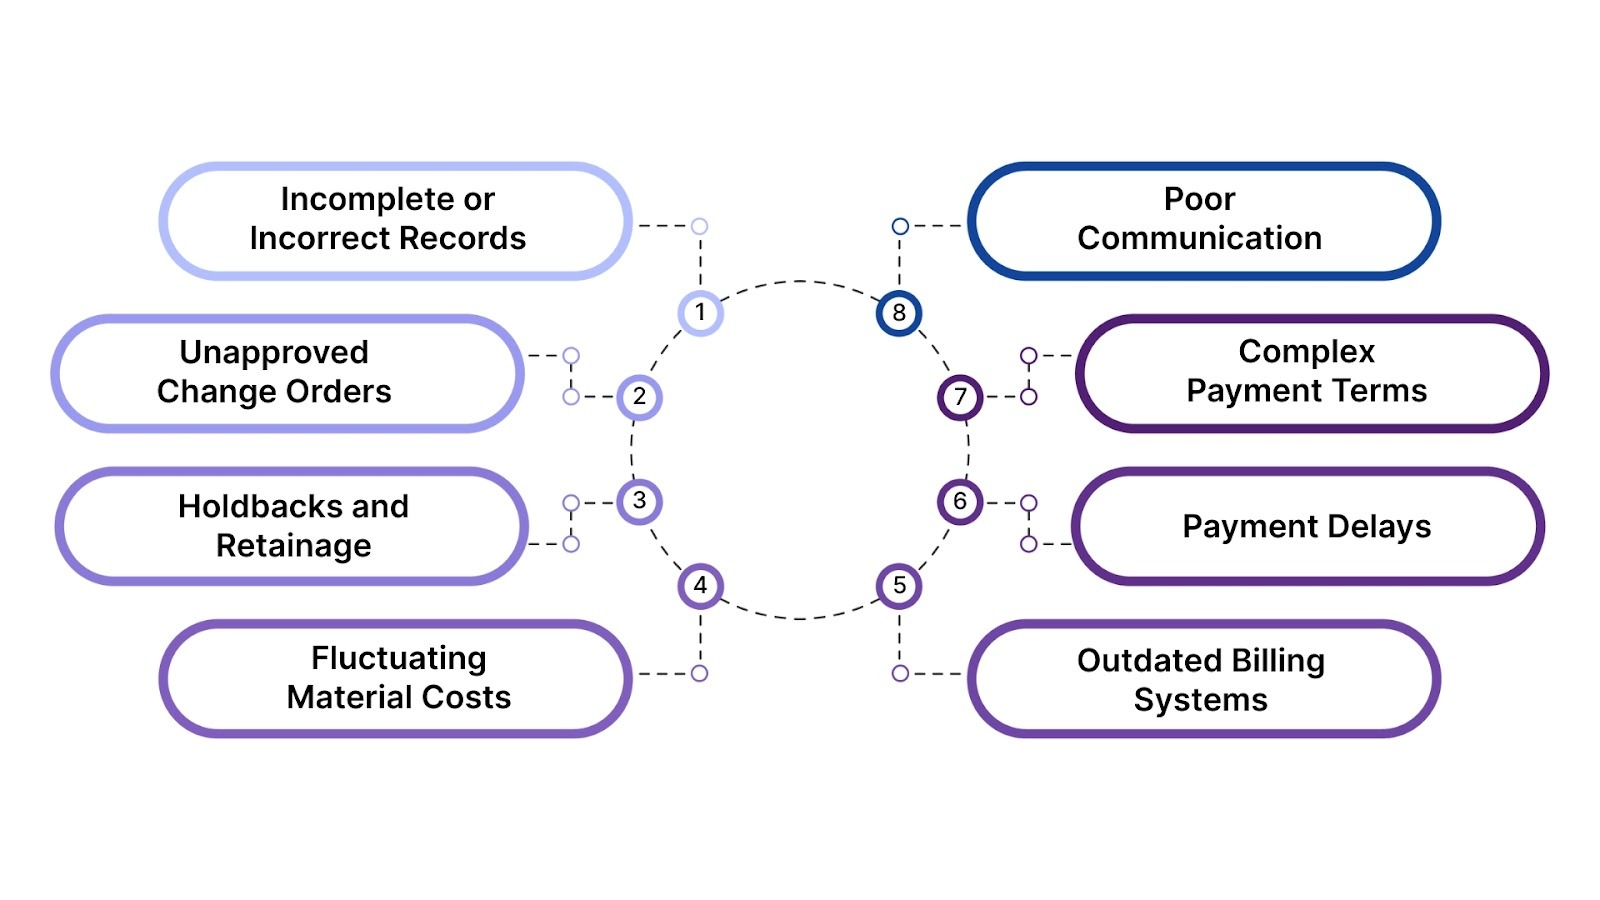
Construction billing can often create delays, cash flow issues, and confusion if not handled carefully. Here is a detailed look at common challenges you may face and how to tackle them effectively:
Missing or inaccurate details in invoices, like wrong quantities or dates, can cause payment disputes and slow down cash flow.
How to Overcome It:
Projects often evolve, and work outside the original scope can cause billing errors if not formally approved.
How to Overcome It:
Clients may withhold a portion of payment until project milestones or final approvals are met, impacting cash flow.
How to Overcome It:
Material prices can change during a project and reduce contractor margins, particularly under fixed-price arrangements.
However, a higher material cost does not automatically mean the contractor can increase the customer’s invoice.
How to Overcome It:
HAL’s newer Construction Cost Management guide specifically documents project budgets versus actual costs, committed spending, subcontractor billing, retention, and change-order tracking.
Manual invoicing or old software increases errors, slows approval, and makes tracking payments difficult.
How to Overcome It:
Late payments are common in construction and can disrupt your project cash flow, delaying work or procurement.
How to Overcome It:
Milestone payments, retainage, and layered contracts can be confusing and lead to miscalculations.
How to Overcome It:
Misunderstandings between contractors, subcontractors, and clients often lead to billing mistakes and disputes.
How to Overcome It:
If these challenges sound familiar, it’s time to upgrade how your construction billing works. HAL helps you manage everything, from project expenses and intercompany billing to VAT compliance and financial reporting, under a single, easy-to-use system.
These common issues can slow down any project, but real-world examples reveal practical ways to overcome them effectively.
Jash Holding, through its subsidiary Jash Technical Services (JTS), operates in facilities management, contracting, logistics, and manufacturing with over 4,000 employees across five companies. They needed a modern solution to unify operations and simplify financial management.
By implementing HAL ERP, Jash streamlined its operations with modules for:
According to HAL’s published Jash Holding case material, the implementation delivered:
HAL’s Jash Holding case study describes how the group replaced fragmented legacy workflows with connected finance, project, payroll, procurement, inventory, and intercompany processes.
These results relate to the broader ERP implementation rather than one billing feature alone, so the case is best used as evidence of integrated project and financial management.
Construction billing works best when invoices are connected to the underlying project costs, contracts, receivables, approvals, and tax records.
HAL Contracting brings project and financial workflows into the same ERP environment. HAL’s current construction content documents support for project costing, subcontractors, procurement, retention tracking, project expenses, and multi-company operations.
Relevant capabilities include:
HAL can support the operational workflow, but the correct billing basis, variation entitlement, retention terms, and VAT treatment still depend on the underlying contract and applicable rules.
Construction billing starts with the contract.
A contractor first needs to determine how the contract price is calculated—for example, lump sum, time and materials, cost-plus, or unit price—and then determine when amounts will be invoiced, such as through progress claims or advance billing.
Retention, approved variations, previous payments, and VAT must then be reflected correctly in each payment claim.
For Saudi projects, contractors should pay particular attention to the ZATCA VAT rules for construction and contracting, especially where the project involves progress invoices, advance payments, retention, or government contracts.
HAL Contracting can connect project costing, subcontractors, procurement, invoicing, expenses, accounting, and multi-company financial workflows in one system.
Businesses evaluating how HAL would fit their construction billing process can request a HAL ERP demo.
There is no single method that is best for every project.
Lump sum is often suitable when the scope is clearly defined, while time and materials or cost-plus arrangements can work better when scope or costs remain uncertain. Unit-price billing is useful when completed quantities can be measured, and progress billing is commonly used on longer projects.
Yes.
For example, a project can have a lump-sum contract price, use monthly progress invoices, receive an advance payment, and have retention withheld from certified payments.
These mechanisms perform different functions and can operate together.
Not really.
Retention is a contractual payment mechanism where part of an amount due is withheld until specified completion or performance conditions are satisfied.
It can apply alongside lump-sum, unit-price, cost-plus, or progress billing.
Saudi construction services are generally subject to 15% VAT.
Because construction is typically treated as a continuous supply, interim invoices, contractual due dates, or payments can create VAT due dates during the project. Certain government contracts have separate timing rules.
Not automatically.
Whether additional costs can be passed to the customer depends on the contract, including any escalation, variation, or change-order provisions. Contractors should document cost changes and obtain the required approval before billing amounts outside the agreed scope or price.